
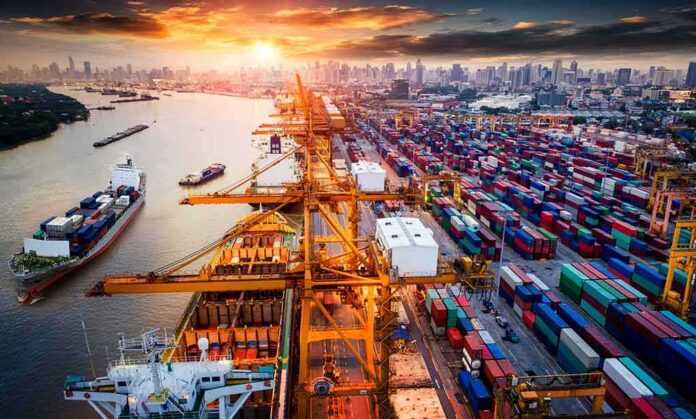
China’s advantage at sea is being forged in its shipyards: an industrial machine that now dominates global commercial shipbuilding is enabling the People’s Liberation Army Navy to commission modern warships at a pace no other navy can currently match.
At a Glance
- China controls a majority share of global shipbuilding and is adding capacity, orders, and backlog simultaneously.
- The PLAN commissioned more than 18 warships in 2025, including the Fujian aircraft carrier, with steady additions continuing into 2026.
- Commercial scale underwrites military throughput; China’s dual-use model links civilian yards and naval production.
- U.S. and allied planners face a numbers-versus-industrial-base problem; rebuilding capacity is measured in decades, not budget cycles.
China’s shipbuilding machine: scale, momentum, and military effects
Start with the numbers that actually move fleets. In 2025, Chinese shipyards completed 53.69 million deadweight tonnes (DWT)—about 56 percent of global output—while capturing roughly 69 percent of new worldwide orders and holding nearly two-thirds of the global orderbook. That is not a one-off spike; it is the product of a system built to compound. New orders and backlog surged again into 2026, with slots reportedly selling out years ahead, indicating the throughput is not just large but durable.
Why does commercial output matter for navies? Because hull fabrication, steel throughput, modular construction capacity, outfitting trades, and supplier ecosystems are fundamentally dual-use. China’s naval shipbuilding does not sit on a thin island of specialized yards; it draws on a dense industrial base whose core processes are validated daily at commercial scale. U.S. and allied analysts have repeatedly emphasized this as the structural enabler of Beijing’s rapid naval expansion—commercial dominance translates into repeatable naval production cycles and the ability to sustain them.
Commissioning tempo: from carriers to combatants
The PLAN’s commissioning cadence reflects this industrial depth. Credible defense reporting tallied more than 18 new warships entering service in 2025, headlined by the commissioning of the Fujian (Type 003) aircraft carrier on November 5, 2025. Additional surface combatants—Type 052D destroyers, Type 055 large destroyers, and a mix of Type 054A and 054B frigates—rounded out the year’s intake, with further ships observed on trials or entering service in early 2026.
This is not mere symbolism. The PLAN’s surface fleet is growing in both tonnage and vertical launch capacity. Across destroyers and frigates alone, 2025 additions represented hundreds of new VLS cells—an index of salvo density and readiness to integrate longer-range air defense and strike weapons. The first Type 054B frigate entered service in January 2025, signaling a new baseline in electric propulsion and combat systems for a workhorse class intended for scale production. The carrier Fujian, with electromagnetic catapults and a displacement exceeding 80,000 tons, anchors a maturing carrier strike enterprise designed for sustained flight operations and high-tempo air wings—capabilities that require the very industrial base China has methodically built.
Mechanism: how the dual-use engine converts scale into naval power
China’s state-owned shipbuilding conglomerates run a portfolio of yards that build the world’s biggest container ships, LNG carriers, and tankers—and the PLAN’s most advanced hulls. The mechanism is straightforward: high commercial throughput funds facilities, anchors a skilled workforce, and amortizes investments in modular construction, heavy-lift cranes, outfitting piers, and supplier tooling. The same block-building techniques and precision welding routines that assemble 400-meter container ships are directly portable to large destroyers and amphibious assault ships. Studies from U.S. and allied think tanks have mapped this integration—about a dozen CSSC-owned yards are responsible for virtually all of China’s modern naval fleet, yet also compete successfully for global commercial contracts.
The result is an industrial metabolism that tolerates complexity and absorbs learning. When a new naval variant arrives—say, a propulsion architecture shift or next-generation radar arrays—the underlying shop floors, logistics, and trades are already scaled. Where Western yards often face a “first-of-class penalty” that cripples schedules across small-batch programs, Chinese yards distribute that penalty across a vast base of repetitive work, then move to cadence faster. This is why orderbook growth matters as much as headline completions: a fat pipeline sustains the labor and supplier continuity that military programs require.
What the numbers do—and do not—tell you
Commercial tonnage is not a perfect proxy for warship output. Submarines and sensitive surface combatants are shrouded in secrecy; precise counts and capability assessments rely on a mix of official ceremonies, satellite imagery, observed pennant numbers, and exercise footage. Analysts rightly caution against reading every commercial record as a naval one-for-one. Still, when multiple strands align—documented PLAN commissionings, visible yard activity across Jiangnan, Dalian, and Hudong-Zhonghua, and sustained commercial backlogs—the inference is sound: China’s naval shipbuilding capacity is real, resourced, and scaling.
On the specifics, open-source defense reporting and state-linked outlets offer convergent signals. The PLAN’s 2025 commissioning tally exceeded 18 hulls, including the Fujian carrier and the first of the 054B frigates, with additional destroyers and auxiliaries spotted entering service into 2026. Commercial metrics from MIIT and industry associations corroborate the industrial base behind these events, showing majority global shares across completions, orders, and backlog.
Implications for the United States and allies
This is an industrial race masquerading as a fleet-count debate. The United States retains advantages in nuclear submarine technology, aviation integration, and combat experience—but those edges erode if ships arrive late, in insufficient numbers, or cannot be repaired quickly after combat damage. China’s core advantage is not a single hull; it is the capacity to build, outfit, and return ships to the fight at scale. Multiple non-Chinese sources—think tanks, trade data, and defense analyses—project the PLAN’s continued numerical expansion this decade, with annual commissioning tonnage outpacing any peer fleet.
The policy translation is uncomfortable but clear. Budgets without yard capacity do not produce ships on time. Industrial ecosystems—steel, heavy forgings, propulsion supply chains, naval electronics, and the skilled trades to assemble and integrate them—must be revived to recover throughput. Partnerships with South Korea and Japan can bridge gaps in the near term; over the long term, only a revitalized domestic base can close the delta in repair and replacement cycles. That timeline is measured in sustained investment and workforce development over decades, not in single-year appropriations or program restructures.
The takeaway
China’s naval rise is not a mystery of strategy; it is a consequence of industrial policy executed at scale. The PLAN’s commissioning pace in 2025 and into 2026 reflects an ecosystem where commercial dominance funds and feeds military production. Counting hulls misses the point. Counting cranes, dry docks, welders, and supplier backlogs does not—and on those measures, China is out in front and widening the gap. For the United States and its allies, matching capability requires matching capacity. There is no shortcut around the shipyard.
Sources:
19fortyfive.com, english.www.gov.cn, asianmilitaryreview.com, faxiangongchang.com, vpk.name, infra.economictimes.indiatimes.com, globaltimes.cn, scmp.com, macaonews.org, xindemarinenews.com, news.cgtn.com, apps.dtic.mil
© impactheadlines.com 2026. All rights reserved.